
SIP vs Fixed Deposit
India’s standard wealth-building playbook has always been simple and based on three steps: earn, save, and put the profit in a bank. The financial landscape is modernising these days, and rapid technological advancement has given it a push for people to uniquely grow and multiply their existing money. To play safe, there has been a debate over whether SIP (Systematic Investment Plans) vs Fixed Deposit (FD) is better. Both avenues offer distinct paths to earn money through interest, but they adhere to entirely different risk appetites, timelines, and financial goals.
Let us understand the key differences and benefits of one against the other:
The traditional money saver machine: FD
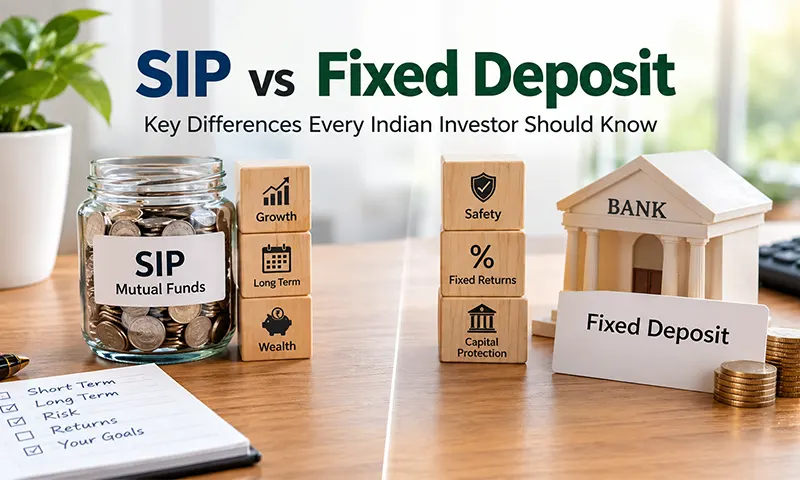
Indian people have long relied on FDs for the best long-term benefits and returns. This is their rigid predictability of assured returns. Opening an FD assures locking up a large sum of money for a fixed tenure in a bank and getting a guaranteed return at a certain interest rate at the end of the tenure or on a monthly or quarterly basis. However, the primary motto is capital protection. In an FD, capital is secured even if there are market crashes or global economic volatility. Also, fixed deposit interest rates are locked at the time of investment, such that whatever is the position of the stock market, at the end of the tenure, an FD holder is assured to get a return at the rate at which he had invested. For senior citizens, the rates are even higher than standard rates, showing a reliable means of income during retirement. However, this safety comes at the hidden inflation of inflation. If inflation is over 6% and FD yields 7%, the real return is virtually negligible.
The modern money builder: SIPs
An SIP is not just an asset but a highly disciplined investment method in mutual funds. One can easily invest a fixed amount, usually monthly, into a chosen fund such as a hybrid portfolio. There have been recent trends showing the rise of SIP investment in India due to increased financial literacy, seamless digital platforms, and middle-class people looking beyond traditional methods for future savings. An SIP leverages the stock market over traditional FDs. When the market is high, the fixed installments buy fewer units in mutual funds, but when the market crashes, the same amount can now buy more units of mutual funds. This technique is called rupee cost averaging, naturally balancing market instability with invested money. SIPs also show discipline by automating deductions from bank accounts on a specific date, making a person forcefully save and keep the funds ready instead of discretionary spending.
Talk of the hour: the debate between SIP and FD depends on the following:
- Wealth accumulation and returns
When analysing SIP vs FD returns, one has to calculate the tenure. FD returns for the short term are secure, but SIP returns for the long term are massive.
- Risk tolerance
The SIP vs FD deposit debate is between risk and certainty. FDs carry no such potent risk, but SIPs carry market risk that can fluctuate.
- Tax efficiency
The SIP vs FD deposit decision is generally influenced on the basis of tax pay.. FD interest is added to the total principal at your marginal rate, but equity SIPs enjoy favourable capital gains taxation.
- Liquidity and flexibility
FDs can be prematurely broken during emergencies with a heavy penalty depending on the tenure or amount that is to be withdrawn, but the FD amount cannot be modified. In SIPs, investment in India, ultimate flexibility is there to pause, add, reduce, or start again with funds.
The ultimate verdict: SIP or FD? Which is better?
When investors ask which one is better, SIP vs FD, the answer is that no size is fit for all; it depends entirely on one’s specific time and need, tenure, and requirements. When saving for a short time, likely a down payment for a house in two years or planning a next-year vacation, or rather building a fund in times of emergency, then FD is the key player based on assured FD interest rates. Short-term market volatility is risky for capital when you need an assured return for a definite investment. However, if no such short-term return or planning is there for fund requirements, then a person can solely depend on SIP. Investment for a goal of five, ten, or twenty years is mathematically superior for long -term goals, and SIP is the undisputed winner there.
Ultimately, the smartest investors do not find a battle between SIP and FD but understand the specific requirement and need to invest, or when and where to invest. A well-balanced asset allocation uses FDs to anchor the portfolio and secure short-term liquidity, while SIPs can aggressively outpace inflation and create massive long-term wealth. Thus, one should understand their distinct roles and then build a financial engine to play safe and secure returns.
